HDB resale prices fell for a third consecutive quarter in the third quarter of 2026, by 0.2%, according to the flash estimate HDB published on 1 October. The headline sounds like a slide. The index says otherwise: 202.4 today against a peak of 203.7 a year ago is a 0.6% decline across three quarters, while resale volumes jumped 17.7% on the quarter, 597 flats changed hands for a million dollars or more, and URA’s private price index rose 1.4% in the same three months. This is a plateau with a widening gap beneath it, not a correction. Here is what moved, what did not, and what to do with it.
Sources: HDB flash estimate and resale statistics (1 Oct 2026); URA flash estimate (1 Oct 2026); The Edge Singapore and EdgeProp (1 Oct 2026).
What did HDB’s Q3 2026 flash estimate actually say?
The Resale Price Index came in at 202.4, down 0.2% from 202.8 in the second quarter, after declines of 0.1% in Q1 and 0.3% in Q2. HDB called it the third consecutive quarter of decline, and said the volume of transactions has remained broadly stable, with 7,528 resale deals recorded up to 29 September against 7,157 in the same period last year.
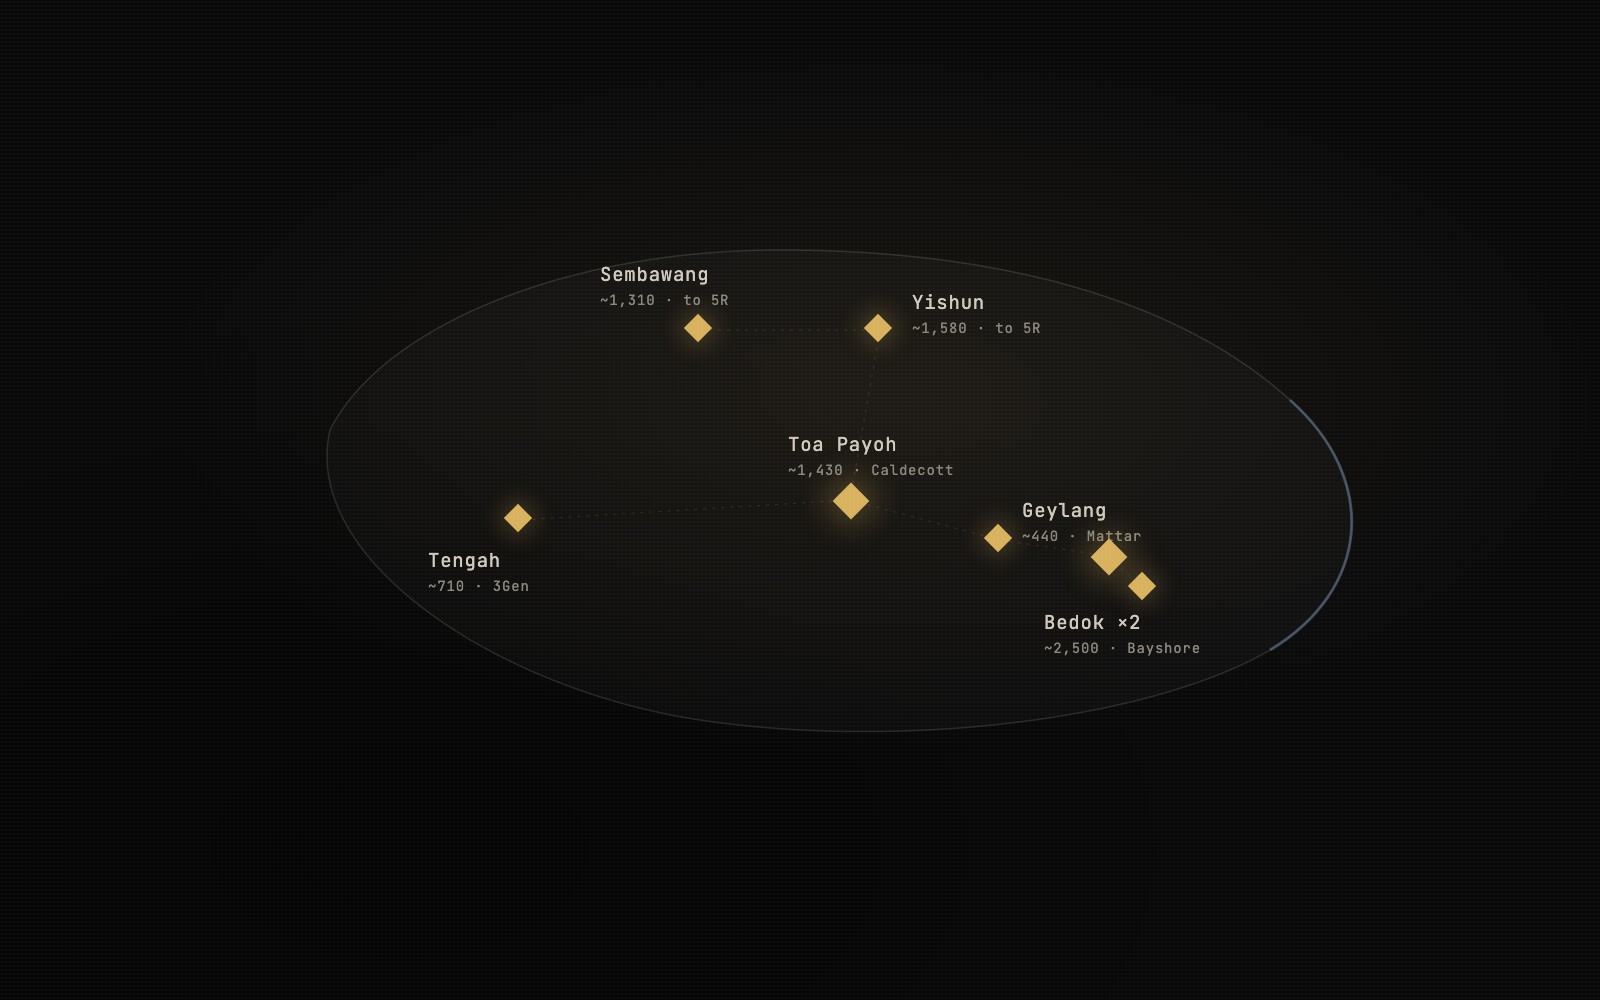
Two other lines in the release matter more than the headline. HDB said it has not observed a significant increase in either the prices or the number of resale flats bought by private property owners and former owners since the 15-month wait-out period was removed on 28 July. And it confirmed the next supply pipe: about 7,960 flats in the November Build-To-Order exercise across Bedok, Geylang, Sembawang, Tengah, Toa Payoh and Yishun, with Community Care Apartments in Toa Payoh. The release closes with the standard caution that the macroeconomic outlook, including interest rates, remains highly uncertain.
Source: HDB. Q3 2026 is the flash estimate. Changes before Q3 2025 are computed from HDB’s published index values.
Eight quarters, from the last big step up to the third straight dip. The bars on the right side of zero are rises; the three on the left are the current run.
Is a three-quarter decline unusual for HDB resale prices?
Not in length, and not yet in size. It is the longest run of quarterly declines since the four quarters to mid-2019, but at 0.6% in total it is a rounding error next to the 12.4% slide from the 2013 peak to the 2019 low, and next to the 56% climb from that low to the peak of September 2025.
Source: HDB Resale Price Index, 1Q2009 = 100. The 2025 to 2026 run includes Q4 2025, which HDB reported as 0.0% on a rounded basis; HDB counts the current run as three quarters.
| Run | Quarters | Index, start to end | Total change |
|---|---|---|---|
| Q3 2013 to Q3 2015 | 9 | 149.4 to 134.6 | −9.9% |
| Q4 2016 to Q1 2018 | 6 | 134.7 to 131.6 | −2.3% |
| Q3 2018 to Q2 2019 | 4 | 131.7 to 130.8 | −0.7% |
| Q4 2025 to Q3 2026 (flash) | 3 to 4 | 203.7 to 202.4 | −0.6% |
The 2013 to 2015 run followed the August 2013 loan curbs and a 30,000-a-year launch programme. The current run has no new curb behind it; the policy moves of 2026 have all loosened demand, from the higher income ceiling to the end of the wait-out period.
That is the context the headline misses. Three dips in a row at this size describe a market that has stopped rising, not one that is falling. Our supply-wave read from last week set a base case of flat to slightly lower into 2027 as flats reaching their Minimum Occupation Period climb from about 13,500 this year to 19,500 in 2028. The flash sits inside that case.
Why are prices slipping while volumes jump 17.7%?
Because supply widened the menu and buyers came back at the new prices. More flats are clearing their MOP, the BTO and Sale of Balance pipes have been enlarged, and the 15-month wait-out is gone, so sellers face more competition at the same time as more buyers are allowed in.
Put the two together and the quarter reads as a repricing, not a retreat. The flats that sold at a million dollars kept selling. The broad index slipped because the middle of the market now has alternatives, and HDB’s own note that private owners did not push prices up confirms the wait-out removal was a demand widener rather than a price shock.
What does private rising 1.4% mean for HDB upgraders?
That the gap widened again. While HDB resale slipped 0.2%, URA’s flash estimate has private prices up 1.4% in the quarter, the eighth consecutive quarterly rise, and the Outside Central Region, where most HDB upgraders buy, up 2.2% after a 0.1% dip in Q2.
Sources: HDB and URA flash estimates, 1 Oct 2026. First nine months: HDB index from 203.6 to 202.4; URA reports an average quarterly rise of 0.9% over the three quarters, about 2.8% cumulative.
| Index | Q2 2026 | Q3 2026 flash | First nine months of 2026 |
|---|---|---|---|
| HDB Resale Price Index | −0.3% | −0.2% | −0.6% |
| URA private, all residential | +0.5% | +1.4% | about +2.8% |
| URA non-landed, Outside Central Region | −0.1% | +2.2% | n.a. |
| URA non-landed, Rest of Central Region | −1.2% | +0.2% | n.a. |
| URA non-landed, Core Central Region | +1.8% | −0.1% | n.a. |
| URA landed | +2.5% | +2.8% | n.a. |
Private sale volume fell about 30% on the quarter to 4,296 deals to mid-September, and new-home sales of about 1,100 units were the weakest third quarter since 1998, per Huttons. Prices rose on a thinner, pricier mix, which is exactly how an index can climb while fewer people transact.
For a household that owns a flat and wants a condo, the arithmetic moved against them for the third quarter running: the asset they sell is flat to down, the asset they buy is up 2.8% on the year with a 1,268-unit Thomson Reserve and Lucerne Grand still to launch. We argued in September that a cooler market is a decision window rather than a dead end, and that still holds, but the window is for people who price the exit first. The muted-growth stretch we flagged in August has extended another quarter on the HDB side, and the private side has not waited.
Where do analysts see the bottom?
Most of them in the fourth quarter, and most of them inside a 1% band for the full year. Huttons expects the HDB resale market to bottom in Q4 2026, and the forecasts published on 1 October cluster tightly, with one outlier.
As reported by The Edge Singapore and EdgeProp on 1 Oct 2026. With the index already 0.6% below its end-2025 level, each call implies a specific fourth quarter.
| House | 2026 resale price call | What that needs in Q4 | Volume call |
|---|---|---|---|
| Huttons Asia | −1% to +1%, bottom in Q4 | Anything from −0.4% to +1.6% | 22,000 to 26,000 deals |
| Singapore Realtors Inc | −1% to +1% | Same band; the low end would be the weakest year since 2018’s −0.9% | n.a. |
| Realion (OrangeTee & ETC) | Stable; headwinds from the higher BTO income ceiling | Roughly flat | n.a. |
| ERA Singapore | +2% to +5% | A Q4 jump of 2.6% to 5.6%, a pace last seen at the end of 2024 | about 26,000 deals |
Our arithmetic on the Q4 column uses HDB’s index of 203.6 at end-2025 and 202.4 at the Q3 flash. A 2.6% quarter last happened in Q4 2024, when the index was still climbing at 9.7% a year; none of the seven quarters since has come close.
What should buyers, sellers and upgraders do now?
What we are watching next
Three dates. URA publishes its full third-quarter statistics on 23 October, when the 1.4% flash can be revised, and HDB typically releases its full quarterly data, including the town and flat-type split, the same day. The November BTO exercise puts 7,960 flats in front of the same buyers the resale market is courting. And the fourth-quarter flash in early January will say whether Huttons’ bottom call held. From 2027, the Primary 1 changes that reserve half the Phase 2C places at 12 schools for families living beyond 2km add a new variable for flats near those schools. We will update this piece when the full quarterly data lands.
Next: what the 2026 to 2028 supply wave does to HDB resale prices →
Sources
- HDB: Flash Estimate of 3rd Quarter 2026 Resale Price Index and Upcoming Flat Supply (1 Oct 2026)
- HDB: Resale Statistics, Resale Price Index Q3 2025 to Q3 2026 flash, and resale applications registered by quarter
- URA: Release of flash estimate for 3rd Quarter 2026 private residential property price index (1 Oct 2026)
- HDB: Removal of the 15-month wait-out period for private residential property owners (27 Jul 2026)
- CNA: HDB resale prices fall for third consecutive quarter: flash estimate (1 Oct 2026)
- The Business Times: Private home prices accelerate with 1.4% rise while HDB resale values dip further in Q3 (1 Oct 2026)
- The Edge Singapore: HDB resale deal volume jumps 17.7% q-o-q in 3Q2026 flash data, market may bottom in 4Q2026 (1 Oct 2026)
- EdgeProp: HDB resale prices dip 0.2% q-o-q in 3Q2026, while transaction volumes surge (1 Oct 2026)
- EdgeProp: Private home prices rise 1.4% despite weakest 3Q new-home sales since 1998 (1 Oct 2026)
Selling an HDB flat into a market where prices slip but volumes jump, or upgrading while the private side pulls away? We price your block to the last 90 days of deals and read the exit before you commit.
Keep reading
Related notes.
More flats are coming. What the 2026 to 2028 supply wave does to HDB resale prices.
HDB resale prices have fallen two quarters in a row, and the flats reaching their five-year MOP rise from about 13,500 this year to 19,500 in 2028. History says supply caps the upside but demand sets the direction. Here is where the softness lands first, and what it means if you are selling to upgrade.
Private prices up 0.5%. HDB down 0.3%. Why cooler is the decision window, not a dead end.
Private prices crawled in Q2. HDB slipped for a second straight quarter. Yet 6,396 resale flats still changed hands, and the 15-month wait-out just came off. Selectivity is the operating system now. That is a decision window, not a dead end.
The November BTO guide: 7,960 flats, six towns, and a deadline in September.
About 7,960 flats across Bedok, Geylang, Sembawang, Tengah, Toa Payoh and Yishun, in the first exercise under the $16,000 income ceiling. The paperwork deadline lands 25 September, and the ballot maths this round is stranger than it looks.
Flash estimates get revised. HDB and URA flash estimates are compiled from transactions up to late or mid-September and are updated when the full third-quarter data is released on 23 October 2026. The Q2 2026 HDB flash of 202.7 was finalised at 202.8. Analyst forecasts are those houses’ views as reported on 1 October 2026, not ours; the fourth-quarter arithmetic in the forecast table is our calculation from HDB’s published index.
Not financial advice. This is market commentary, not a recommendation to buy or sell any property. Speak to us or your own adviser about your situation.
Independent. The Property Collective is a team within PropNex Realty and is not affiliated with HDB, URA or any of the research houses quoted.