Three numbers set the shape of Singapore’s property market in 2027. About 15,000 HDB flats reach the end of their five-year Minimum Occupation Period, up from 13,500 this year and 8,000 in 2025, on the Government’s own count. Not a single executive condominium reaches its MOP between October 2025 and January 2028, so resale EC stock is frozen for two years. And 9,704 private homes and ECs are due to complete, 29% more than in 2026, before the pipeline peaks in 2028. Set those against a population that grew by 97,300 people in a year and adds roughly 23,000 households annually, and 2027 reads as a year of plentiful HDB supply, scarce resale ECs, a private launch backlog, and borrowing costs rising from a low base. Here is each piece with its source, and what it asks of you.
Sources: MND speech of 22 Jan 2026 (OrangeTee’s project-level count for 2027 is 18,939); EdgeProp project data and developer TOP records; URA Q2 2026 real estate statistics, Annex E-3.
What does 2027 look like in one table?
Most of 2027 is already written, in tender results, completion schedules and five-year clocks that started ticking in 2022. The table puts the supply, demand and cost figures side by side, with 2026 for scale. Everything that follows explains one row.
Sources in the final column; full citations at the end of the article. Figures as at 9 October 2026.
| Measure | 2026 | 2027 | Source |
|---|---|---|---|
| BTO flats launched | 19,600 planned | At least about 15,700; HDB says it is likely to exceed its 55,000 target | HDB, MND |
| Of which shorter-wait flats, under 3 years | Over 4,000 | About 4,000 | MND |
| HDB flats reaching MOP | 13,500 (OrangeTee: 13,484) | 15,000 (OrangeTee: 18,939) | MND, OrangeTee |
| ECs reaching MOP | None | None | Project TOP dates |
| New EC supply with a 5-year MOP | Five sites awarded, about 1,970 units | The last launches under the old rules | HDB |
| Private homes and ECs completing | 7,495 | 9,704 | URA |
| Private units launched by developers | MND expected about 12,000; 4,727 by September | The 2026 shortfall rolls over; 33,963 unsold units in the pipeline | MND, Huttons, URA |
| GLS Confirmed List supply | 9,320 units, over 50% above the 10-year average | 1H2027 list due in December 2026 | URA |
| 3-month compounded SORA | About 1.2% in October, from about 1% in Q2 | Maybank forecasts 1.6% at end-2026 and 1.85% at end-2027 | ST, BT |
| Population | 6.21 million, up 97,300 in a year | Next count in September 2027 | NPTD |
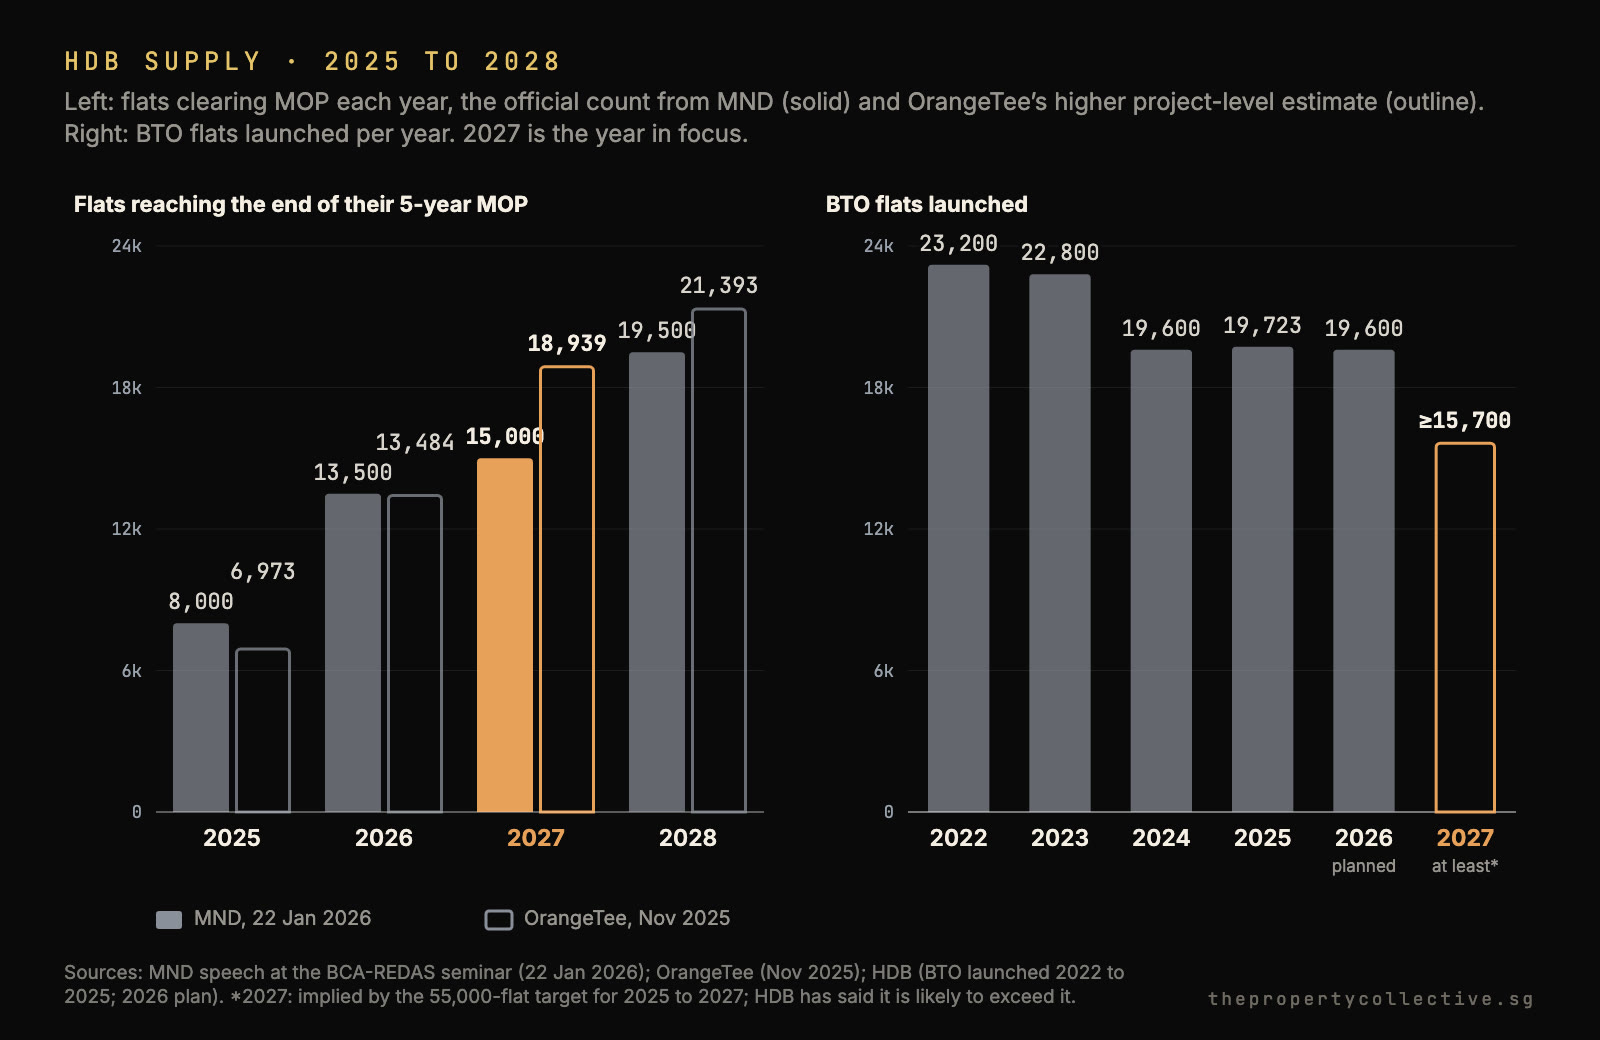
The 2027 BTO figure is what the 55,000-flat target for 2025 to 2027 implies after 19,723 flats in 2025 and 19,600 planned for 2026. Minister Chee Hong Tat said in May that HDB is likely to exceed the target, and HDB said in June that it is prepared to offer more than 55,000 flats if necessary.
How much HDB supply arrives in 2027?
Two pipes, both wide open. The first is flats clearing their MOP. In January, National Development Minister Chee Hong Tat put the cohort at 13,500 flats in 2026, 15,000 in 2027 and 19,500 in 2028, against 8,000 in 2025. OrangeTee, counting project by project from HDB’s property information, gets 13,484, 18,939 and 21,393. We treat the Minister’s number as the floor and OrangeTee’s as the ceiling. Either way, 2027 adds more newly eligible resale flats than 2026 did, and 2028 adds more again.
The second pipe is new flats. HDB launched 19,723 BTO flats in 2025 and plans 19,600 in 2026, which leaves about 15,700 to reach the 55,000 promised for 2025 to 2027. Mr Chee said in May that HDB is likely to exceed that target, and HDB repeated in June that it is prepared to offer more than 55,000 flats if necessary. About 4,000 of the 2027 flats will carry waits under three years. Add the Sale of Balance Flats exercises, which supplied 10,252 units in 2025, and first-timers keep a steady choice of new flats through 2027.
Demand gets a push at the same time. The BTO income ceiling rose from $14,000 to $16,000 for HFE letters applied for from 24 August 2026, the singles ceiling from $7,000 to $8,000, and from the February 2027 sales exercise first-timer families receive an extra ballot chance for each citizen child aged 18 and below. The November 2026 exercise, about 7,960 flats in Bedok, Geylang, Sembawang, Tengah, Toa Payoh and Yishun, is the first under the new ceiling, and Mr Chee said in May that a 1,600-unit project beside Caldecott MRT in Toa Payoh West would be in it. We covered the ceiling change when it was announced.
What this does to prices is already visible. HDB’s resale price index fell 0.1% in the first quarter, 0.3% in the second and 0.2% in the third on the flash estimate, three straight quarterly declines, while volumes held up: 7,528 resale transactions in the third quarter, 5.2% more than a year earlier, and 24 flats sold above $1.5 million, 60% more than the quarter before. HDB also reports no significant rise in purchases by private owners since the 15-month wait-out period was removed on 28 July. Our read for 2027: the index moves within a band of about minus 2% to plus 1%, volumes rise with the MOP cohort, and the split we described in the supply-wave piece widens. The towns that carried the 2026 cohort, Punggol, Queenstown, Tampines and Toa Payoh, and whichever towns carry 2027’s, see the softest prices; scarce five-room and central flats keep setting records.
Why does no EC reach its MOP in 2027?
Because almost nothing was completed in 2021 and 2022. An EC can be resold five years after its Temporary Occupation Permit, and the launch calendar of 2018 and 2019 was thin. Rivercove Residences, 628 units in Sengkang, launched in 2018 and received TOP on 2 October 2020. Piermont Grand, 820 units in Punggol, launched in 2019 and received TOP on 3 January 2023. Nothing sits between them. Rivercove cleared its MOP on 2 October 2025; Piermont Grand clears on 3 January 2028. For all of 2026 and 2027 the resale EC market gets no new project at all, after 1,386 units became eligible in 2024.
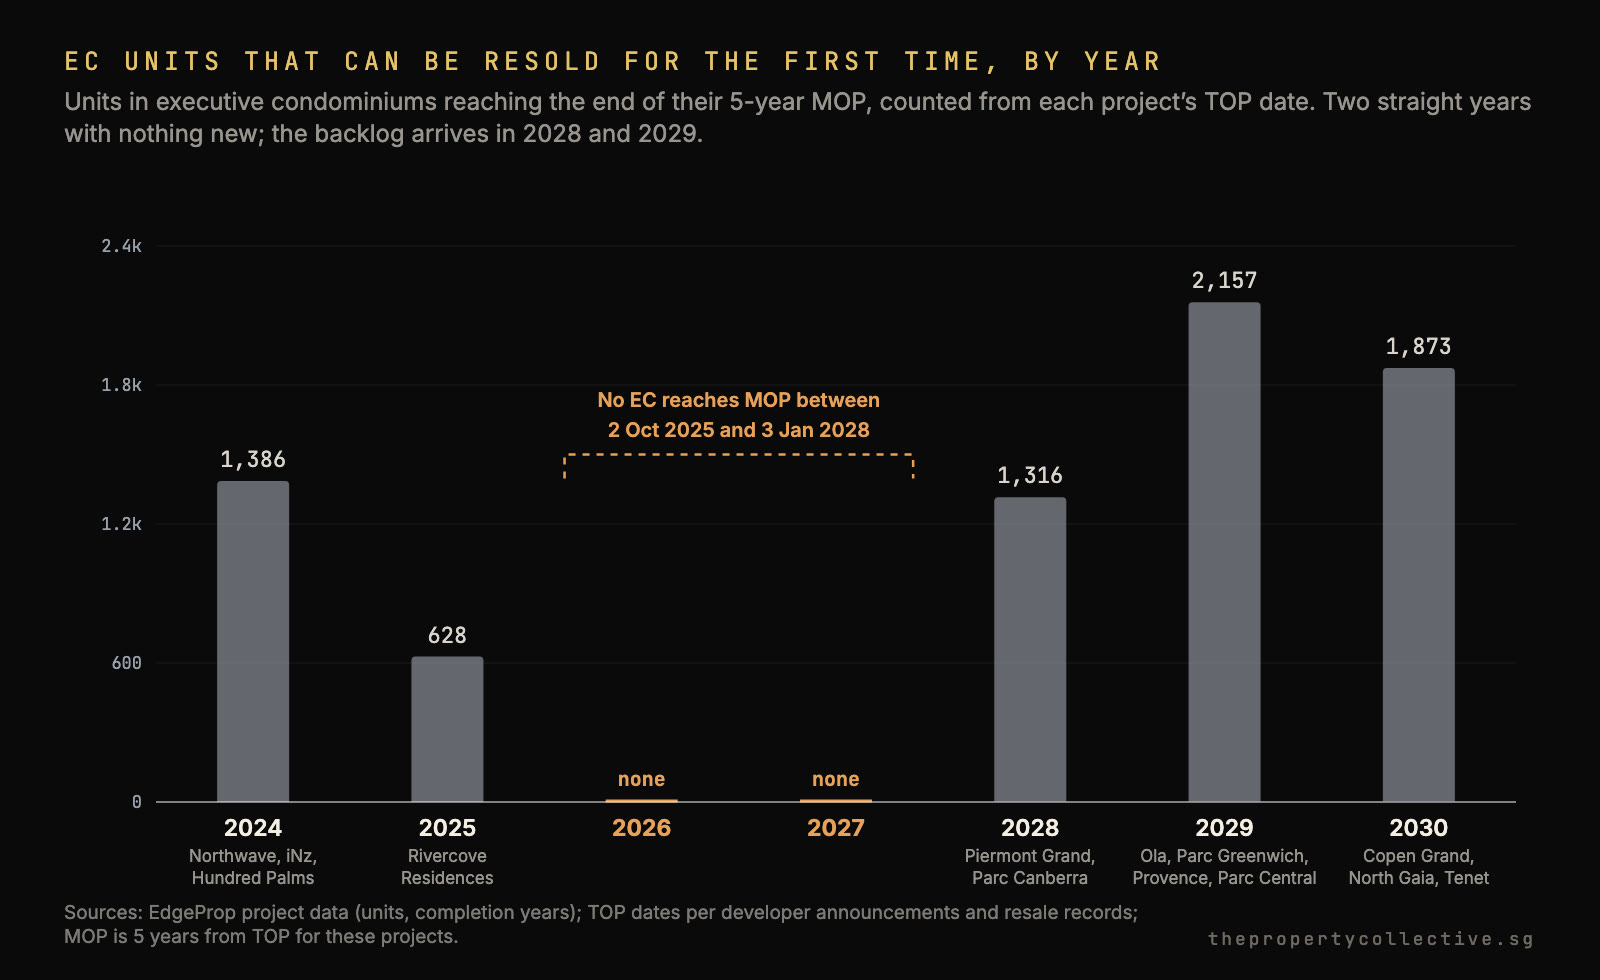
Sources: EdgeProp project data for unit counts and completion years; TOP dates from developer announcements and resale listing records. MOP for these projects is five years from TOP; ECs on land tendered from 8 May 2026 carry a 10-year MOP.
| Project | Units | TOP | MOP ends |
|---|---|---|---|
| Rivercove Residences, Sengkang | 628 | 2 Oct 2020 | 2 Oct 2025 |
| Piermont Grand, Punggol | 820 | 3 Jan 2023 | 3 Jan 2028 |
| Parc Canberra, Sembawang | 496 | Sep 2023 | Sep 2028 |
| Ola, Sengkang | 548 | 29 Apr 2024 | 29 Apr 2029 |
| Parc Greenwich, Sengkang | 496 | 9 May 2024 | 9 May 2029 |
| Provence Residence, Sembawang | 413 | 3 Jun 2024 | 3 Jun 2029 |
| Parc Central Residences, Tampines | 700 | 18 Jul 2024 | 18 Jul 2029 |
| Copen Grand, Tengah | 639 | Apr 2025 | Apr 2030 |
| North Gaia, Yishun | 616 | Jul 2025 | Jul 2030 |
| Tenet, Tampines | 618 | Sep 2025 | Sep 2030 |
Sing Holdings’ 2025 annual report confirms North Gaia’s July 2025 TOP; Tenet’s September 2025 TOP is from resale listing records, as EdgeProp’s project page still shows its original estimated completion year.
Three consequences follow. Owners at the ECs that cleared MOP in 2024 and 2025, Rivercove, Hundred Palms, iNz Residence and Northwave, hold the only fresh resale EC stock in Singapore until 2028, which is pricing power. Upgraders who want an EC in 2027 must buy new, and the new supply is the last under the old rules: five sites tendered before 8 May 2026, at Senja Close (about 295 units), Woodlands Drive 17 (about 420 and 560 units on two plots), Sembawang Road (about 265) and Miltonia Close (about 430), keep the five-year MOP and may still offer the Deferred Payment Scheme, and their launches are expected through 2027. After them come the 10-year-MOP projects, starting with Canberra Drive, where a record $825 psf ppr land bid in October points to launch prices near $1,900 psf. We compared the five old-rule plots here, and set out what the May rules change.
How big is the private pipeline in 2027?
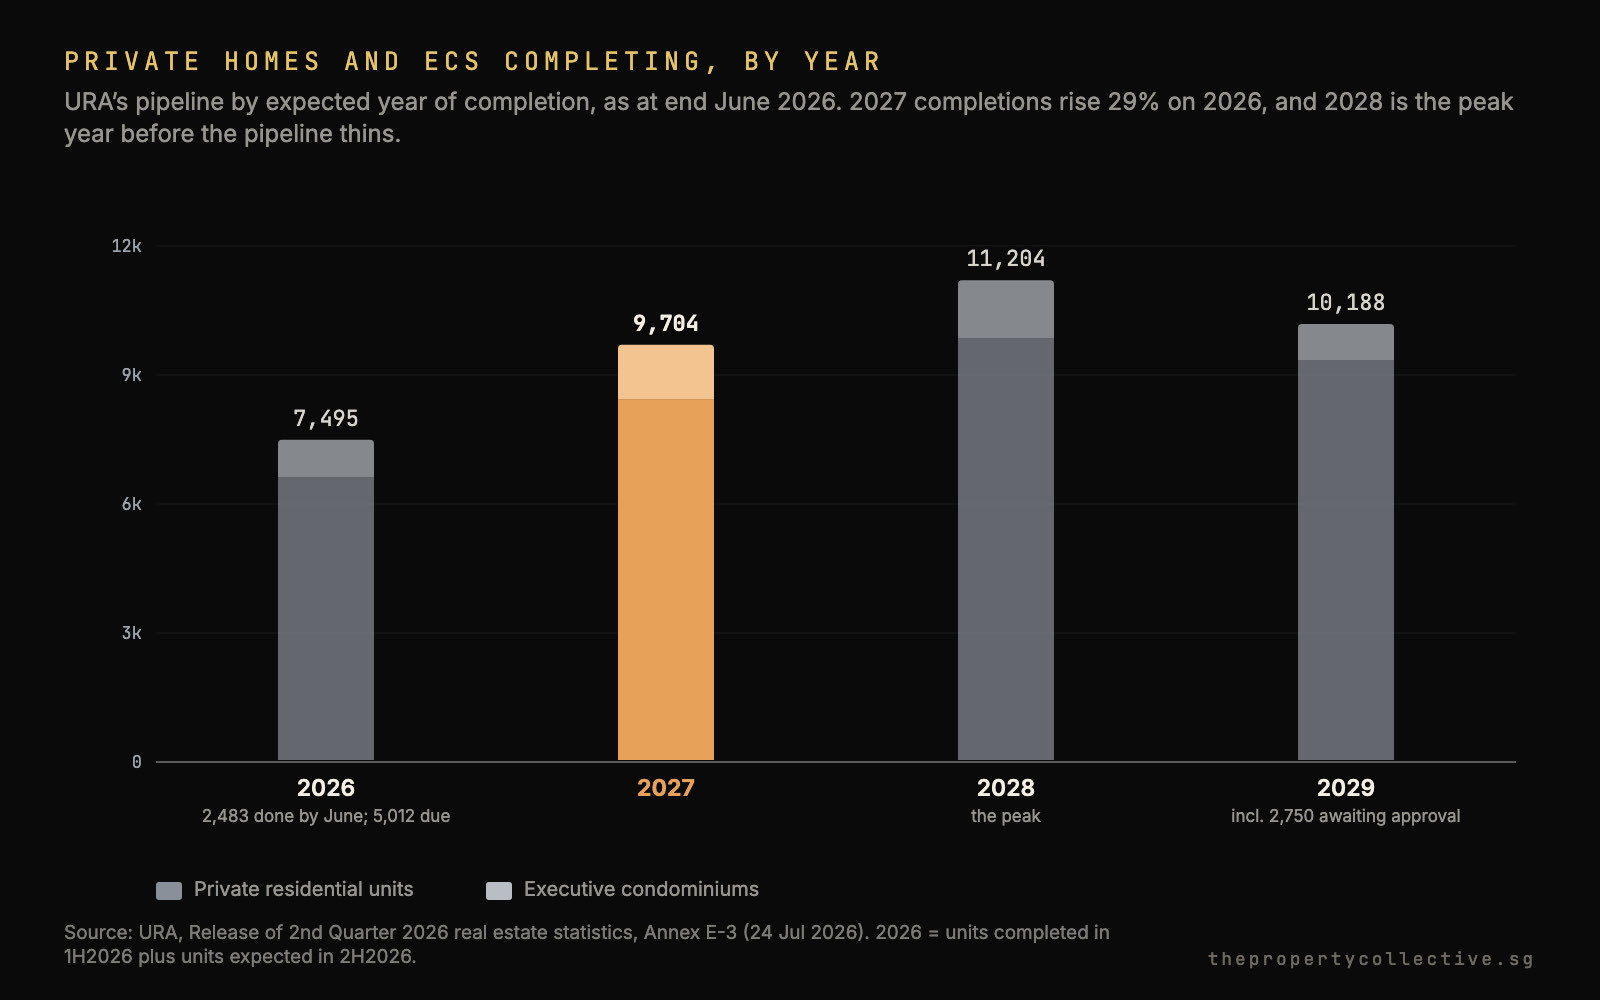
Bigger than this year, and still below the peak. URA’s completion schedule puts 9,704 private homes and ECs at TOP in 2027, against 7,495 for 2026, which is 2,483 completed by June plus 5,012 due in the second half. 2028 is the top of the cycle at 11,204, and 2029 holds 10,188 including units not yet granted planning approval. The vacancy rate of completed private homes was already 6.4% at end-June, up from 6.2%, with rents up 0.7% in the second quarter. More keys in 2027 and 2028 is the main reason we expect rents to stall.
Launches are the other half, and 2026 fell short. In January MND expected developers to launch about 12,000 private units this year, including en-bloc and EC projects. Huttons counts 4,727 launched in the first nine months, 46.6% fewer than a year earlier, with the third quarter, at about 1,100 units, the smallest third quarter on record. The fourth quarter brings Thomson Reserve (1,268 units), Lucerne Grand (570) and The Serra (133), but the year will still finish well under 12,000. The difference does not vanish; it rolls into 2027. URA counts 15,810 unsold units with planning approval and another 18,153 without, 33,963 in all, of which about 32,000 could be released for sale within two years or so. The 2026 Confirmed List alone adds land for 9,320 units, more than 50% above the ten-year average.
Launch timing is each developer’s decision; this is the pipeline with land already sold or on tender, not a launch schedule. Sources: URA, HDB, developer announcements and our GLS coverage.
| Project or site | Homes | Status |
|---|---|---|
| One Chuan Grove, Lorong Chuan (Sing Holdings and Sunway) | about 1,055 | Two adjacent GLS plots awarded on 17 July and 10 September 2025 for $1.33 billion; the developers plan one project and are marketing a 2027 launch |
| New Upper Changi Road GLS, Bedok | about 1,010 | Record $1,537 psf ppr land bid in 2026 |
| Berlayar Drive GLS, Telok Blangah | about 415 | Sole bid at $1,515 psf ppr; about 745 more homes on the Kingsford plot beside it |
| Lorong Puntong GLS, Thomson | about 140 | Seven bids, $1,612 psf ppr |
| Five EC sites: Senja Close, Woodlands Drive 17 (two plots), Sembawang Road, Miltonia Close | about 1,970 | The last ECs with a 5-year MOP |
| Canberra Drive EC, Sembawang | about 185 | First EC tendered under the 10-year MOP; award pending |
| Admiralty Walk EC, Sembawang | about 450 | Tender closes 17 Dec 2026 |
| Jurong Lake District white site | up to 1,200 | Launched for tender on 3 July 2026; closes 17 November 2026 |
Price direction is set by the land under those projects. The URA index rose 1.4% in the third quarter on the flash estimate, its eighth straight quarterly gain, and 2.8% for the year to September; landed prices are up 4.9% this year, OCR non-landed prices rose 2.2% in the quarter and the Core Central Region slipped 0.1%. The share of new-sale transactions above $2 million jumped from 52.3% to 71.7% between the second and third quarters. With 2026 land bought at $1,500 to $1,600 psf ppr in the suburbs and the city fringe, the next launch is unlikely to be cheaper than the last. Our read for 2027: the index gains 2% to 4%, led by new launches, while resale prices in completed projects lag and the gap between the two widens.
Does the population support this much supply?
Yes for occupancy, less clearly for ownership. Singapore’s population reached 6.21 million in June 2026, up 97,300 in a year: 70,300 more non-residents, 24,200 more citizens and 2,800 more permanent residents. NPTD attributes the non-resident growth mainly to Work Permit holders in construction, for Changi Terminal 5, the Marina Bay Sands expansion and the housing ramp-up itself; they live in dormitories, not in the flats and condos being built. The buyers are in the other lines. 25,094 people were granted citizenship and 35,352 permanent residency in 2025, and resident households rose 1.6% to 1.49 million, about 23,000 more households in a year.
Family formation is weaker. Citizen marriages fell 5.6% to 21,671 in 2025 and citizen births fell 10.8% to 26,071; the resident total fertility rate is 0.87, and 19.5% of residents are now 65 or older. Fewer marriages mean fewer new BTO households each year over time, while an ageing population generates right-sizing supply. That is the demand backdrop for a 2027 that completes about 9,700 private homes and, if HDB keeps its 2025 pace of roughly 19,600 completions, close to 30,000 new homes in all: more than the 23,000 households the country added last year.
Sources: SingStat Population Trends 2026; NPTD Population in Brief 2026; URA Q2 2026 Annex E-3; HDB; MND; OrangeTee.
| Line | Figure |
|---|---|
| Resident households added, 2024 to 2025 | about 23,000 |
| Citizen marriages in 2025 | 21,671 |
| Citizenships and permanent residencies granted in 2025 | 25,094 and 35,352 |
| Private homes and ECs completing in 2027 | 9,704 |
| HDB flats completed in 2025, our proxy for 2027 | about 19,600 |
| Resale flats newly eligible in 2027 | 15,000 to 18,939 |
| Resale ECs newly eligible in 2027 | 0 |
HDB has not published a completion figure for 2027; 127 projects were under construction in January 2026, up from 110 a year earlier, so the 2025 pace is a conservative proxy. Completions are keys, not sales: most of these homes were bought years earlier, so the near-term price effect runs through rental listings and resale supply rather than new demand.
What do interest rates do to affordability in 2027?
They rise from a low base, and the stress test does not move. Three-month compounded SORA bottomed near 1% in the second quarter and sits around 1.2% in October, after the US Federal Reserve’s September increase to 3.75–4%, its first since 2023. DBS expects one more Fed increase in 2026 and another by the first quarter of 2027; Maybank forecasts SORA at 1.6% at end-2026 and 1.85% at end-2027. Banks have already moved: several fixed packages crossed 2% in the first week of October, with Maybank’s three-year fixed at 2.55% and OCBC’s at 2.08%. The HDB concessionary loan stays at 2.6%.
Our arithmetic, principal and interest only. Banks assess TDSR and MSR at the higher of 4% or the loan’s thereafter rate, so the loan you qualify for does not change when SORA moves; your monthly cash flow does.
| Rate | Instalment |
|---|---|
| 1.2%, roughly SORA today before the bank’s spread | $3,309 |
| 1.5%, the cheapest packages of mid-2026 | $3,451 |
| 2.0%, where fixed packages sit in October | $3,696 |
| 2.5%, the top of current three-year fixed offers | $3,951 |
| 3.0% | $4,216 |
| 4.0%, the MAS stress-test floor | $4,774 |
The practical reading: a household borrowing $1 million pays about $245 a month more at 2% than at 1.5%, and about $1,080 less than at the 4% rate the bank tested it at. 2027 is not a cheap-money year like 2021, nor a repeat of the 3% to 4% years of 2023 and 2024; it is a 2%-ish year with upside risk. That argues for fixing part of the loan and sizing the rest to the stress rate, not for waiting. We set out the Fed path and what it means for your mortgage here, and how TDSR and MSR actually cap you here.
What is on the 2027 calendar?
Confirmed dates from HDB, URA and MND; launch timings are expectations, not announcements.
| When | What | Who it affects |
|---|---|---|
| Nov 2026 | BTO exercise: about 7,960 flats in six towns, the first under the $16,000 ceiling | First-timers |
| 3 Dec 2026 | East Coast Road GLS tender closes, about 85 homes in Siglap | East Coast buyers and owners |
| 17 Nov 2026 | Jurong Lake District white site tender closes, up to 1,200 homes | West-side buyers, developers |
| Dec 2026 | 1H2027 Government Land Sales programme announced | New-launch buyers, developers |
| 17 Dec 2026 | Admiralty Walk EC tender closes, about 450 homes, the second under the 10-year MOP | EC buyers |
| Early Jan 2027 | Q4 2026 flash estimates from URA and HDB; HDB’s 2027 BTO plan usually follows | Everyone |
| Feb 2027 | BTO exercise with an extra ballot chance per citizen child | First-timer families with children |
| Through 2027 | The five old-rule EC launches; One Chuan Grove and the 2026 GLS sites | Upgraders, new-launch buyers |
| Mid 2027 | P1 registration under the new Phase 2C rules: 60 places, with 12 schools split | Parents near popular schools |
| Through 2027 | 9,704 private homes and ECs receive TOP | Tenants, landlords, nearby resale sellers |
| 3 Jan 2028 | Piermont Grand clears its MOP: the first new resale EC stock since October 2025 | EC buyers and sellers |
HDB usually announces the coming year’s BTO programme in January, and URA announces each half-year GLS programme in June and December.
Two of those dates reshape who is buying. The P1 changes are covered in our piece on homes near top schools, and the wait-out removal, which widens the pool of resale flat buyers through 2027, in this one.
What should you do in 2027?
What would change this read?
Next: the 2026 to 2028 supply wave and what it does to HDB resale prices →
Sources
- MND: Speech by Minister Chee Hong Tat at the BCA-REDAS Built Environment and Real Estate Prospects Seminar (22 Jan 2026)
- The Straits Times: 19,600 BTO flats to be launched this year; 2027 supply to increase if demand stays strong (8 Jan 2026)
- The Straits Times: HDB likely to exceed initial 55,000-flat target from 2025 to 2027 (8 May 2026)
- HDB: Launches 6,952 Flats Across 7 Projects in June 2026 BTO Sales Exercise
- HDB: Increase in Income Ceilings and Greater Support for Families with Children (23 Aug 2026)
- HDB: Flash Estimate of 3rd Quarter 2026 Resale Price Index and Upcoming Flat Supply (30 Sep 2026)
- HDB: 25,000 New Flats will be Launched in 2025 (BTO flats launched 2021 to 2025)
- HDB: Launches 9,144 Flats across 10 Projects in October 2025 BTO Sales Exercise (2025 totals)
- The Straits Times: Over 13,400 HDB flats to reach MOP in 2026 (28 Dec 2025)
- OrangeTee: HDB quarterly data, MOP supply projections
- URA: Release of 2nd Quarter 2026 real estate statistics, including Annex E-3 (24 Jul 2026)
- URA: Private housing supply under the GLS programme sustained at a high level in 2H2026 (3 Jun 2026)
- The Business Times: Private home prices accelerate with 1.4% rise while HDB resale values dip further in Q3 (1 Oct 2026)
- EdgeProp: Private home prices rise 1.4% despite weakest 3Q new-home sales since 1998 (Oct 2026)
- NPTD: Population in Brief 2026 (25 Sep 2026)
- SingStat: Population Trends 2026 (25 Sep 2026)
- The Straits Times: S’pore population rises 1.6% to 6.21 million (25 Sep 2026)
- EdgeProp: Executive condominium projects, units and completion years
- CDL: FY2025 results (Copen Grand TOP in April 2025)
- HDB: tender launches at Senja Close, Woodlands Drive 17, Miltonia Close and Sembawang Road (2025)
- The Straits Times: S’pore mortgage rates rise following Fed hike (2 Oct 2026)
- The Straits Times: US aligns inflation policy with other central banks with first rate hike since 2023 (Maybank SORA forecasts)
- MAS: Calculating TDSR, medium-term interest rate floor
Planning a 2027 move, a sale at MOP, an EC application or a first private purchase? We run the supply in your town, the exit and the loan on your own numbers before you commit.
Keep reading
Related notes.
One bid, $1,243 psf ppr: what EL Development’s Marina Gardens Lane offer means for Marina South and One Marina Gardens.
The Marina Gardens Lane tender closed on 15 October with a single envelope: EL Development at $450.1 million, or $1,243 psf per plot ratio. That is 11% below what Kingsford paid next door for One Marina Gardens, and under the $1,350 to $1,650 analysts expected. Here is what the number does to the precinct, to One Marina Gardens’ buyers, and to anyone waiting for a cheaper way in.
Three quarters down, 0.6% in total. What HDB’s Q3 flash really says about resale prices.
HDB’s flash estimate puts the Q3 2026 Resale Price Index at 202.4, down 0.2% and the third straight quarterly dip, while URA’s private index jumped 1.4%. Volumes rose 17.7%, million-dollar flats hit 597, and the gap between an HDB flat and the condo it is meant to fund widened again. Here is what the number does and does not mean.
Two new land sales: 85 homes in Siglap now, 235 in Serangoon North later, and what each one prices in.
URA released two residential sites on the same day: a 0.55-hectare plot on East Coast Road, Siglap’s first residential state land since the Seaside Residences site, where every unit must average at least 100 sqm, and a 235-home Reserve List plot at Serangoon North View beside The Garden Residences. One goes to tender on 3 December with analyst calls from $1,100 to $1,650 psf ppr. The other is a signal that says not yet. Here is what each one prices in.
Our read. The price, rent and volume expectations in this article are The Property Collective’s own reading of the published supply, demand and rate data as at 9 October 2026. They are ranges, not predictions, and we will revise them when URA and HDB publish full third-quarter data in late October, when HDB announces its 2027 BTO programme, and after each GLS announcement.
EC dates. Unit counts and completion years for executive condominiums are from EdgeProp’s project data; TOP dates are from developer announcements and resale listing records, as HDB does not publish a register of EC TOP dates. MOP is five years from TOP for every project named; it is 10 years for ECs on land with tenders closing on or after 8 May 2026.
Arithmetic. Loan instalments are principal and interest on a $1 million, 30-year loan at a constant rate, our calculation. The 2027 home-completion total adds URA’s 9,704 to HDB’s 2025 completions as a proxy, because HDB has not published a 2027 figure. The household figure is SingStat’s 1.6% growth applied to 1.46 million households.
Illustration. The header image is an AI-generated illustration of a Singapore housing estate, not a photograph of any project named here.
Not financial advice. This is market commentary, not a recommendation to buy or sell any property. Speak to us or your own adviser about your situation.
Independent. The Property Collective is a team within PropNex Realty. PropNex and other houses’ research is quoted where named; we are not affiliated with HDB, URA, MND, MAS or any developer named here.